 By Saurav
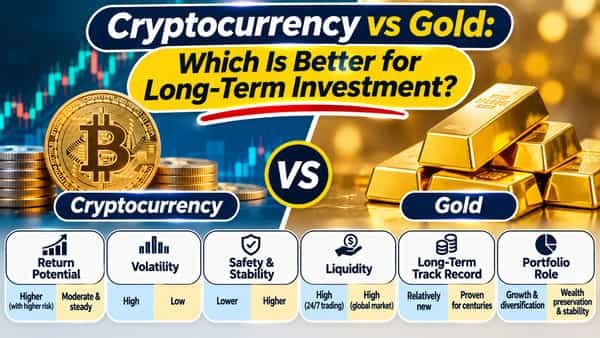
For long-term investment, neither cryptocurrency nor gold is clearly better, because they offer different bargains: gold gives a long track record, lower volatility, and a modest but steady role as a store of value, while cryptocurrency offers a much younger asset with far higher potential upside and far deeper, more uncertain downside. Over a decade or more, the gap between the two comes down less to which one “wins” and more to when you start, how large a position you hold, and whether you can stay invested through painful stretches. Thinking in terms of roles and risk budgets, rather than picking a champion, tends to produce better decisions. This is general information, not investment advice, so consider speaking to a qualified adviser and a tax professional about your own situation.
What “Long-Term” Changes
Time horizon reshapes the comparison in several ways.
- Short-term noise matters less. Over many years, day-to-day swings fade, but large drawdowns and structural shifts still matter.
- Compounding magnifies differences. Even a few percentage points of annual return diverge widely across decades.
- Survival matters. The key long-term question is whether the asset will still be widely valued in 10 or 20 years.
- Behaviour matters. Many investors sell at the worst moment, so an asset you can hold calmly may outperform one with a higher theoretical return that you abandon.
The Track Record Over Long Periods
- Gold: valued for thousands of years, with price rising in many long stretches and stagnating in others. In the 1980s and 1990s it went through multi-year periods of weakness after the 1980 peak before recovering. It reached record highs of roughly $5,600 an ounce in January 2026 and had risen strongly from early 2025.
- Bitcoin: a track record of about 17 years. Over the past decade it has delivered far higher annualised growth than gold, with one 2026 comparison citing roughly 62% a year for Bitcoin against roughly 12.6% for gold. Yet it has also had several drops of 70% to 85% from peak to trough, and traded well below its October 2025 high of around $126,000 for much of 2026.
- Other cryptocurrencies: most have far shorter histories, and many that once ranked among the largest have faded.
Starting dates swing these comparisons dramatically, so be wary of any single chart.
Drawdowns and Recovery: The Hidden Cost
Long-term returns are only useful if you survive the declines on the way.
- Gold’s worst drawdowns have typically been in the range of 30% to 45%.
- Bitcoin’s worst drawdowns have been in the range of 75% to 85%.
- Recovery maths is unforgiving: after a 40% fall, an asset must gain about 67% to break even, after a 75% fall it needs 300%, and after an 80% fall it needs 400%.
- Time underwater: recovery can take years. Gold spent decades below its 1980 peak in inflation-adjusted terms, while Bitcoin has historically taken a few years to reclaim prior highs, though past recoveries don’t guarantee future ones.
Why Position Size Matters Most
Because crypto is so volatile, how much you allocate often matters more than whether you choose it. A simple illustration of the damage a deep fall can cause to a whole portfolio, assuming crypto falls 80%:
- At a 5% allocation, the portfolio loses about 4%
- At 10%, it loses about 8%
- At 20%, it loses about 16%
- At 50%, it loses about 40%
By comparison, if gold fell 30% on a 20% allocation, the portfolio would lose about 6%. A small crypto position can add potential upside without endangering your plan, while a large one puts your long-term goals at the mercy of a single volatile asset.
Inflation and Purchasing Power
- Gold has historically preserved purchasing power over very long periods, though it can lag for years and isn’t a perfect inflation hedge in any single year.
- Bitcoin is often described as an inflation hedge because of its capped supply of 21 million coins, but its short history and large swings mean the evidence is limited, and it has often traded like a risk asset when markets fall.
- Neither pays income, so their returns depend entirely on price changes, unlike shares that can pay dividends or bonds that pay interest.
What Could Go Wrong Over Decades
For gold:
- Long stretches of flat or falling prices, as in the decades after 1980
- Rising real interest rates, which make non-yielding assets less attractive
- Changes in central bank buying or investor sentiment
For cryptocurrency:
- Regulatory shifts that restrict or favour particular activities
- Technological obsolescence, where newer networks replace older ones
- Security failures or protocol flaws
- Loss of confidence that could cause prolonged declines
- Custody and key-management failures by owners over many years
Crypto also carries a “survival” risk that gold doesn’t: the possibility that a given coin becomes irrelevant.
Costs of Holding for the Long Run
- Gold: physical gold involves making charges on jewellery, a gap between buying and selling prices, storage, and insurance. Exchange-traded gold funds charge a small annual expense ratio.
- Cryptocurrency: trading spreads, network fees, and custody costs. Self-custody has no ongoing fee but requires secure backups and planning, and exchange custody relies on the platform.
- Holding costs compound, so even small annual fees matter over decades.
Custody and Practicality Over Time
- Gold can be held in familiar forms, such as coins, bars, funds, and bonds where available, and heirs generally know what to do with it.
- Crypto requires safeguarding keys or relying on a platform, and an heir may be unable to access it without clear instructions. Estate planning matters more than many owners realise.
- Access over decades: gold’s market has existed for centuries, while crypto exchanges, wallets, and regulations are still evolving.
Taxes in India (Rules Can Change)
- Gold: physical, jewellery, and digital gold held for more than 24 months are taxed at 12.5% on long-term gains without indexation, while listed gold ETFs qualify after 12 months, also at 12.5%. Shorter holdings are taxed at slab rates. GST applies when buying physical gold.
- Cryptocurrency: gains are taxed at a flat rate regardless of how long you hold, with limited deductions, no offsetting of losses against other income, and a 1% TDS on eligible transfers. Holding longer doesn’t earn a lower rate.
For long-term investors, gold’s lower tax rate after the holding period can be a meaningful advantage, so check the current provisions and consult a professional.
How They Behave Together
- Correlation changes over time. At times gold and Bitcoin have moved together, and at other times in opposite directions.
- Gold has often held up better in market stress, while Bitcoin has sometimes fallen alongside stocks.
- A blend can balance roles: gold as the steadier ballast, and a small crypto allocation as a higher-risk growth slice. Neither is guaranteed to protect you in every downturn.
Who Might Lean Which Way
Gold may suit long-term investors who:
- Prioritise capital preservation and lower volatility
- Want a traditional diversifier with a very long history
- Prefer familiar, regulated holding options
- Have a lower tolerance for large drawdowns
Cryptocurrency may suit long-term investors who:
- Have a long horizon and can tolerate drawdowns of 70% or more
- Hold a small allocation they can afford to lose
- Are comfortable with technology, custody, and regulatory uncertainty
- Believe in continued adoption of the technology
Many choose both, sized to their goals, with gold typically larger and crypto smaller.
A Simple Long-Term Framework
- Define the job each asset does in your portfolio.
- Set allocations in advance, such as a modest gold share and a small crypto slice, and write them down.
- Invest gradually, for example monthly, to reduce timing risk.
- Rebalance on a schedule, trimming what has grown too large and adding to what has lagged.
- Plan custody and inheritance, especially for crypto.
- Mind taxes and costs when comparing returns.
- Keep an emergency fund and diversify across other assets so you never have to sell at a bad time.
- Review annually, not daily.
Frequently Asked Questions
Q1. Has crypto outperformed gold over the long term?
A. Over the past decade Bitcoin has outperformed gold by a wide margin, but with far deeper drawdowns, and results depend heavily on the starting date.
Q2. Is gold safer than crypto over the long term?
A. Gold has a longer record and has been much less volatile, though neither is risk-free and both can lose value for years.
Q3. How much crypto is reasonable in a long-term portfolio?
A. Many people keep it to a small share that they could comfortably see fall by 80% or more, but the right amount depends on your goals and risk tolerance.
Q4. Which is taxed less in India for long-term holders?
A. Gold held beyond the required period is taxed at a lower flat rate on gains, while crypto gains face a flat rate and TDS regardless of holding time, but check the latest rules.
Q5. Can I hold both gold and crypto?
A. Yes, many investors do, using gold for stability and a smaller crypto position for growth potential.