 By Kartikey Bhatt
A small business can be profitable on paper and still struggle to grow because it does not have enough cash at the right time. A manufacturer may need new machinery, a retailer may need inventory before the festive season, or a growing startup may need to hire employees months before additional revenue arrives. This is where business financing becomes important.
For Indian small-business owners, two major routes are debt financing and equity financing. Debt means borrowing money that generally has to be repaid with interest. Equity financing means raising capital from investors in exchange for an ownership interest in the business.
The difference may sound simple, but the long-term consequences are significant. Debt allows owners to retain ownership but creates repayment obligations. Equity can reduce immediate repayment pressure but means sharing future business value and potentially some control.
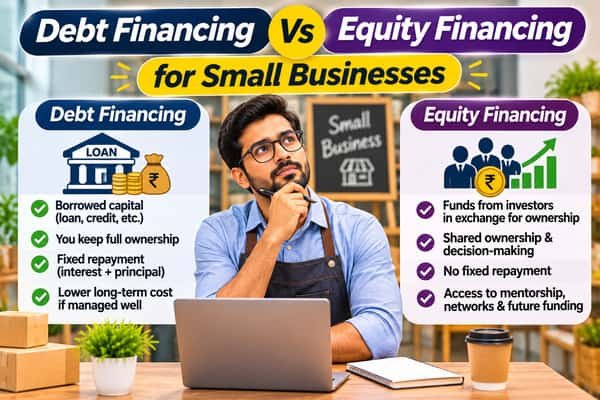
The better choice depends on your cash flow, business structure, risk, growth plans and the purpose for which money is required.
Debt Financing Vs Equity Financing: Quick Comparison
| Factor | Debt Financing | Equity Financing |
|---|---|---|
| Basic Structure | Borrowed money | Capital for ownership stake |
| Repayment | Usually required | No conventional loan repayment |
| Interest | Usually applicable | No loan interest |
| Ownership Dilution | No | Yes |
| Founder Control | Generally retained | May be shared |
| Cash-Flow Pressure | Higher due to repayments | Usually lower initially |
| Investor/Lender Return | Interest and repayment | Growth in investment value/distributions |
| Security | May be required | Generally not structured as collateralised lending |
| Suitable For | Predictable cash-flow businesses | High-growth or higher-risk ventures |
| Funding Availability | Depends on creditworthiness | Depends on investor interest |
| Main Risk | Repayment burden/default | Ownership dilution and governance implications |
What Is Debt Financing?
Debt financing means obtaining money with an obligation to repay it according to agreed terms.
For Indian businesses, debt can take several forms, including:
- Term loans
- Working-capital loans
- Cash-credit facilities
- Overdrafts
- Equipment or machinery finance
- Business loans
- Invoice-related financing
- Other eligible MSME credit facilities
The lender does not normally become an owner simply because it provides a conventional business loan.
Instead, the business agrees to repay the principal along with interest and applicable charges.
Debt can therefore be attractive when an owner needs capital but does not want to give another person an ownership stake.
What Is Equity Financing?
Equity financing involves raising capital in exchange for an ownership interest.
Depending on the business structure and transaction, equity investors may include:
- Founders
- Angel investors
- Venture capital funds
- Strategic investors
- Private investors
Equity financing is particularly associated with companies and startups capable of issuing shares or other permitted securities.
Not every small-business structure can raise equity in the same way. For example, a sole proprietorship cannot simply issue company shares to an investor. The legal structure may therefore need consideration before pursuing equity investment.
Debt Lets Existing Owners Retain Their Equity
The most obvious advantage of debt is that the owner does not ordinarily surrender part of the business to the lender.
Imagine you own 100% of a company and borrow ₹20 lakh for expansion.
If the business grows substantially and the loan is eventually repaid, you can still retain your ownership, assuming no other equity transactions take place.
With equity financing, raising ₹20 lakh may require giving an investor a percentage of the company.
If the business becomes extremely valuable later, that percentage could be worth far more than the original investment.
This is why founders often describe equity as having no fixed interest bill but potentially being very expensive in terms of future ownership.
Debt Creates Regular Cash-Flow Pressure
The biggest challenge with borrowing is repayment.
A business may need to pay interest and principal even when:
- Sales decline
- Customers delay payments
- Seasonal demand falls
- A major customer leaves
- Inventory remains unsold
This makes debt particularly risky for businesses with unpredictable cash flows.
Before borrowing, calculate whether the business can comfortably service the debt under conservative conditions.
Do not calculate repayment ability using only your best month.
Stress-test the numbers by asking:
What happens if revenue falls by 20–30% for several months?
If loan repayments would immediately create a cash crisis, the proposed debt level may be too aggressive.
Equity Does Not Create Normal EMI Obligations
Equity investment generally does not operate like a traditional loan with monthly principal and interest repayments.
This can give a growing business breathing room.
A startup may use investor capital to develop technology, build a team or acquire customers before becoming profitable.
This is particularly useful when the business requires substantial investment before it can generate stable cash flow.
However, equity is not free money.
Investors expect the value of their investment to increase and may seek an eventual return through mechanisms such as:
- Sale of their stake
- Acquisition of the company
- Future investment rounds
- Public listing in suitable cases
- Other agreed exit opportunities
Equity replaces repayment pressure with ownership and performance expectations.
Interest Makes Debt Easier to Quantify
One advantage of debt is that its financial cost can be more predictable.
Suppose you borrow money at an agreed interest rate. Subject to the loan terms and any variable-rate conditions, you can estimate the cost of borrowing.
Equity does not have the same fixed cost.
Imagine an investor receives 20% ownership for an early investment.
If the company later becomes worth ₹50 crore, that stake could potentially be worth ₹10 crore before considering transaction terms, dilution or other factors.
That can make successful equity extremely valuable to the investor.
On the other hand, if the business fails, an equity investor can lose a significant part or all of the investment.
Debt May Require Security or Guarantees
Depending on the loan, lender and borrower’s profile, debt financing may involve:
- Collateral
- Personal guarantees
- Business guarantees
- Financial statements
- Bank records
- Credit assessment
- Cash-flow evaluation
Not every business loan requires property collateral, and India has various credit schemes and lending products for eligible MSMEs.
However, business owners should read the complete lending terms carefully.
A “limited liability” business structure does not necessarily protect a promoter from a personal guarantee voluntarily given to a lender.
Understand exactly what assets or guarantees support the borrowing.
Equity Can Change Decision-Making
When you accept an equity investor, you are bringing another owner into the business.
The level of influence depends on the investment arrangement.
Investors may negotiate rights relating to:
- Board representation
- Major expenditure
- Additional fundraising
- Business sale
- Share transfers
- Financial reporting
- Certain strategic decisions
A minority investor does not automatically control the company, but investment documents can create important rights.
Founders should therefore evaluate the investor as carefully as the investor evaluates them.
The highest valuation is not necessarily the best deal if the working relationship becomes difficult.
Debt Is Often Suitable for Predictable Business Needs
Debt can work particularly well when the borrowed money has a clear purpose and the business has sufficient cash flow to repay it.
Examples include:
- Purchasing machinery
- Adding delivery vehicles
- Financing confirmed orders
- Buying seasonal inventory
- Expanding a profitable outlet
- Funding short-term working-capital requirements
Suppose a manufacturer buys a machine that immediately increases production capacity and revenue. If expected cash flows comfortably cover loan payments, borrowing can be commercially sensible.
The key is connecting debt to realistic economic returns.
Equity Is Often Better for High-Risk Growth
Equity may be more appropriate when future returns could be large but cash flow is currently uncertain.
For example, a technology startup may spend significant money developing a platform before generating substantial revenue.
Large loan repayments during this period could create severe pressure.
Equity investors may be willing to accept this risk because they participate in the company’s potential upside.
This makes equity particularly relevant for:
- Technology startups
- New platforms
- Research-intensive ventures
- Rapid expansion strategies
- Businesses entering large new markets
However, conventional small businesses may find it harder to attract equity investors because investors usually seek meaningful growth potential.
Consider the Purpose Before Choosing Funding
The same business can use different financing methods for different needs.
A company might use equity to develop a new product while using equipment finance to purchase machinery.
Ask three questions before raising money:
- How much capital do I actually need?
- When will this investment start generating cash?
- Can the business repay debt even if growth is slower than expected?
These questions are often more useful than simply asking which financing method is cheaper.
Can Small Businesses Use Both?
Yes. Financing does not always have to be exclusively debt or equity.
A growing company might use a combination.
For example:
- Founders invest initial equity.
- A bank provides working-capital finance.
- An investor later funds expansion.
- Equipment is purchased using suitable asset financing.
Using multiple sources can prevent excessive dependence on one financing method.
But too much complexity can also create problems.
Owners should monitor:
- Total debt
- Interest obligations
- Ownership dilution
- Cash runway
- Investor rights
- Future funding requirements
The capital structure should support the business rather than become a burden.
Debt Financing Vs Equity Financing: Which Is Better?
Consider debt financing when:
- Cash flow is reasonably predictable.
- You want to retain ownership.
- The business can comfortably service repayments.
- The capital has a clear revenue-generating purpose.
- Borrowing terms are commercially reasonable.
Consider equity financing when:
- The business needs substantial growth capital.
- Current cash flow cannot support large repayments.
- The opportunity has significant scaling potential.
- You are willing to dilute ownership.
- A suitable investor can contribute capital and strategic value.
For many established Indian small businesses, carefully managed debt can be practical because owners retain their equity. For early-stage, high-growth businesses with uncertain cash flows, equity may provide more flexibility.
The best financing is not necessarily the one with the lowest visible cost. It is the one that gives the business enough capital to grow without creating unsustainable repayment pressure or giving away more ownership than necessary.
FAQs
Q1. Can a small business get debt financing without collateral?
A. Possibly. Some lenders and eligible MSME financing programmes offer collateral-free or differently secured credit depending on the borrower’s eligibility, credit profile and scheme conditions. Collateral-free does not mean approval is automatic or that no guarantee or documentation will ever be required.
Q2. Does equity financing have to be repaid?
A. Equity is generally not repaid like a conventional loan with fixed EMIs. However, investors receive an ownership interest and expect a financial return from the growth or future distribution/exit of their investment.
Q3. Can a sole proprietorship raise equity investment?
A. A sole proprietorship does not have shares like a company. If an outside investor needs formal ownership, the entrepreneur may need to consider an appropriate business structure such as a partnership, LLP or company depending on the proposed arrangement.
Q4. Should I take a business loan if my company is not yet profitable?
A. It depends on cash flow rather than profit alone, but borrowing becomes riskier when the business cannot reliably service repayments. Prepare realistic cash-flow projections, including a downside scenario, before accepting debt.